
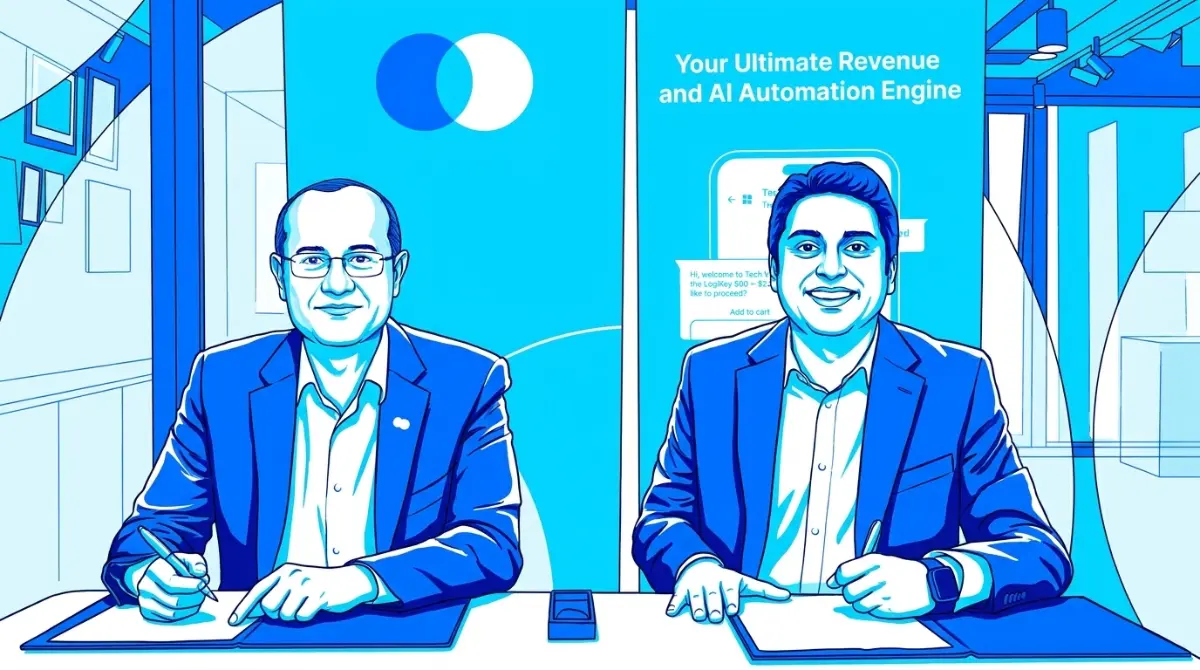


Mastercard And Flowcart Debut WhatsApp Pay in Kenya
Mastercard unites with conversational platform Flowcart to turn WhatsApp into an end-to-end storefront across Kenya, challenging mobile money dominance through in-chat card checkout.
Inioluwa Ademidun | 7 Sept. 2026 · 5 min read

Standing in the center of Nairobi's bustling commercial districts two years ago, I watched a boutique fashion vendor run an entire retail empire from a cracked smartphone. She did not operate a storefront website, maintain a digital catalog on Shopify, or swipe customer cards through bulky point-of-sale hardware. Her entire sales funnel lived inside direct messaging channels: sending photos of imported dresses, answering customer questions in real time, and copying numerical account prompts back and forth. Yet every single transaction hit an awkward wall the moment money had to change hands. Customers were forced to leave the chat, punch codes into external accounts, and manually paste transfer receipts back into the conversation to prove they paid. That clunky friction has cost regional businesses untold sales. Now, two financial giants are betting they can erase that gap entirely.
Global card network Mastercard has allied with conversational retail specialist Flowcart to introduce direct card settlement inside WhatsApp across Kenya. Rather than forcing shoppers onto third-party checkout portals or external billing applications, the rollout allows consumers to discover merchandise, assemble orders, and settle balances without leaving the chat thread. The initiative starts on Kenyan soil before expanding into regional hubs including South Africa, Nigeria, and Cote d'Ivoire.
My years tracking digital finance across African capitals have shown me that Western product assumptions constantly fracture against local consumer habits. Global venture funds spent billions trying to train African consumers to shop on standalone browser sites, only to discover that everyday internet users preferred social feeds and messaging rooms. In Kenya today, WhatsApp alone processes more than 20% of all online shopping orders, officially beating out legacy web storefronts. By placing payment rails directly where shoppers spend their waking hours, this alliance meets modern merchants on their home turf.
Closing the In-Chat Checkout Loop
The operational engine behind this rollout pairs Flowcart's retail software with Mastercard Gateway payment rails. When a potential buyer messages an enterprise brand or a small boutique seller, conversational algorithms assemble ready-to-buy shopping baskets directly from natural dialogue. If a customer inquires about fabric colors, stock availability, or package sizes, the software updates the order on the fly. Once the shopper confirms the order, the screen displays a native checkout prompt powered by tokenized card credentials, embedded web links, or quick-response payment codes.
Flowcart, which processes approximately $3M in monthly transaction volume across its existing footprint, has zeroed in on the exact spot where chat-based shopping typically breaks down. Most conversational tools can hold automated discussions, but they leave the final payment step disconnected. By bringing the settlement mechanism directly into the conversation, merchants can capture spontaneous purchase intent before the buyer gets distracted or abandons the deal. The software also helps stores win back customers who walked away from unfinished orders on regular websites by sending automated reminders that let them pay directly inside chat.
Shehryar Ali, senior vice president and regional manager for East Africa and the Indian Ocean Islands at Mastercard, emphasized that the deployment expands digital acceptance across underserved and informal mercantile groups. The timing coincides with acute merchant demand: the 2026 Mastercard SME Confidence Index revealed that 80% of Kenyan small enterprises view straightforward, user-friendly settlement options as the most important requirement for business survival.
Challenging the Mobile Money Orthodoxy
The deeper strategic story sits in the battle over payment networks. For nearly two decades, Kenya has stood as the undisputed kingdom of mobile network billing, where Safaricom's M-Pesa shaped consumer habits and locked up domestic payments. Card networks found themselves largely pushed out of everyday peer-to-peer and neighborhood retail transactions, relegated instead to high-end supermarket chains, international flight bookings, and wealthy expat expending.
Embedding card settlement into the nation's most popular messaging channel represents a clever flank against mobile network dominance. Social sellers who could never justify renting traditional terminal hardware can now accept international and local debit cards with zero physical equipment. It opens an avenue for card schemes to collect transaction fees on small, informal retail purchases that previously flowed exclusively through domestic telecom accounts. When looking at how telecom groups defend regional markets, payment rails are where these corporate empires collide.
Whether micro-merchants will embrace card checkout depends heavily on the underlying transaction fees, which neither partner has disclosed publicly. In price-sensitive emerging markets, fractional percentage differences on merchant processing fees decide whether a vendor keeps a payment tool or abandons it. If card processing cuts too deeply into seller margins, vendors will continue steering shoppers toward low-cost peer-to-peer phone transfers, regardless of how elegant the chat interface appears.
The Continental Push for Conversational Commerce
Kenya is serving as an early testing ground for a wider continental race toward messaging-first retail. From Lagos to Johannesburg, tech platforms are racing to turn chat apps into transactional powerhouses. While Meta has moved slowly in activating native checkout features for its African messaging apps, external financial networks are filling the void. Regional fintech platforms like Nomba expanding cross-border payment rails and major card networks recognize that conversational commerce represents the true digital high street of the continent.
The collaboration also signals an expansion beyond consumer retail into routine municipal payments. The underlying payment architecture is designed to support airtime recharges, municipal utility bills, and basic educational fees. For public utilities and telecom companies, shifting these routine interactions into messaging accounts drastically reduces customer service overhead while speeding up collections.
The romantic vision of African retail being conquered by standalone Silicon Valley-style software applications is officially over. The future of commerce across these markets is happening inside chat threads, negotiated in colloquial shorthand, and completed through swift digital handshakes. By turning WhatsApp into a frictionless cash register, Mastercard and Flowcart are positioning themselves at the center of the continent's informal economic engine.
Read More on TechRobust:
Inioluwa Ademidun
 LinkedIn
Inioluwa Ademidun
Expertise:African Tech Ecosystem, Early-Stage Startups, Emerging Market Dynamics, Venture Capital & Tech Reporting, Product Management
Award:TechRobust Contributor of the Year 2025
Inioluwa is a Senior Product Manager by day and an investigative technology reporter by night, bridging the gap between scalable software architecture and high-impact journalism. She delivers deep-dive analysis on venture-backed founders, regulatory shifts, and grassroots tech ecosystems across Africa and global emerging markets.